30 Mar 20263 min
Connected laundry: from payment to a completed cycleA practical laundry journey connecting availability, payment, machine activation and customer support.
Read article →3 min · Updated 03 Oct 2026
Organize costs, utilization and discounts before changing a service price.
More revenue does not automatically mean a better laundry result. A discount may attract additional cycles while consuming capacity during an already busy period. Before changing prices, review service costs, equipment utilization and customer experience. The calculations below are illustrative; real values must come from the site’s agreements and operating records.
List water, energy, consumables, payment fees and other expenses associated with a cycle. Distinguish these from rent, staffing, connectivity and periodic maintenance. Not every expense changes with each sale, and mixing categories makes service comparisons harder. If a measurement is unavailable, label the estimate as an assumption and plan to verify it rather than treating it as a confirmed figure.
For illustration only, suppose a cycle sells for 20 monetary units and its variable expenses total 8. The difference is 12 to contribute toward fixed expenses and operating results. With a discount of 2 and unchanged variable expenses, that difference becomes 10. It is not net profit. The example shows why looking only at cycle volume can hide a discount’s effect. Use the operation’s actual currency and values.
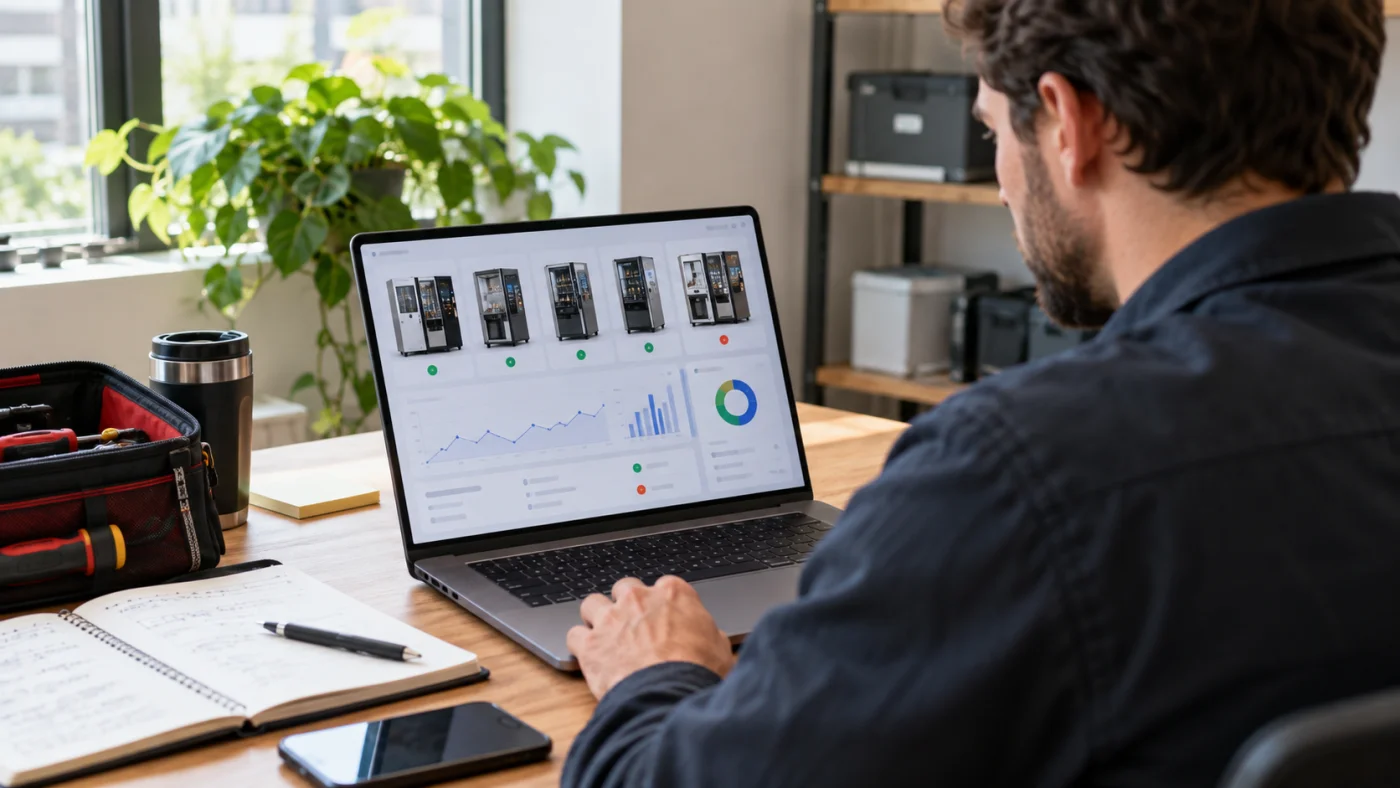
An off-peak offer may redistribute demand, but its effect needs measurement. Compare equivalent periods and record weather, holidays, machine outages and other conditions. Review utilization by equipment, waiting time and complaints alongside revenue. Higher sales when more machines were available do not prove that the price change caused the improvement.
Display the total price, eligible service, offer period and limits before payment. Check that the app, kiosk and support team use the same configuration. Pilot the rule at one site, record its outcome and define its end date. Ask the accounting team to confirm cost classifications; an operational worksheet does not replace the company’s financial statements.
Self-service technology and operations
Cicclo editorial content helping operators connect payments, equipment and management. Examples are illustrative and should be adapted to each operation.
A practical laundry journey connecting availability, payment, machine activation and customer support.
Read article →
PIX and cards need a clear link between the transaction, the selected machine and the confirmed cycle.
Read article →
A practical approach to classifying alerts, investigating causes and coordinating maintenance with context.
Read article →Understand connectivity, fresh telemetry, operational availability and confirmed cycle events.
Read article →